Cato Networks
Israel · owned by Independent (Israel) · www.catonetworks.com · 20 vendors
Cato Networks is the pioneer of the Secure Access Service Edge (SASE) category, offering a cloud-native platform that converges SD-WAN, network security, and remote access into a single global service. The platform delivers capabilities including Zero Trust Network Access (ZTNA), Firewall-as-a-Service, Secure Web Gateway, AI-powered threat prevention, and extended detection and response (XDR) to over 4,000 enterprise customers worldwide. Co-founded by Shlomo Kramer (also co-founder of Check Point Software and Imperva), Cato Networks is recognized as a Leader in the Gartner Magic Quadrant for SASE Platforms.
Resilience scores
- Digital Sovereignty: 5
- Digital Resilience: 9
- Financial Resilience: 8
Technology vendors
- Adobe Inc. — Technology — United States
- Anthropic, PBC — Technology — United States
- Stripe, Inc. — Financial Services — United States
- and 17 more
Services catalogue
1 service in catalogue across 1 category; runs on 20 sub-vendors.
- SASE Cloud
Insights
Last updated 2026-07-09 · revision 3
20 direct vendors, 307 subvendors
Direct vendors by controlling owner country (sample)
- Japan: 1
- United States: 16
- France: 1
Subvendors by controlling owner country (sample)
- Denmark: 6
- Finland: 1
- Netherlands: 7
Migration Readiness: 5/10
Assessed by AI based on technology stack characteristics (cloud-native vs legacy, containerization, microservices), regulatory environment, data residency requirements, financial stability, and vendor lock-in risks. The score ranges from 0-10, where higher scores indicate better readiness for technology migration.
Cato Networks exhibits a medium level of migration readiness, primarily due to the unique nature of its core infrastructure. Its 'custom cloud-native software stack' and 'GraphQL API' indicate a modern architectural approach that is inherently flexible and automatable. The company's internal systems largely leverage SaaS solutions like Salesforce, Jira, Slack, Okta, Splunk, and ServiceNow, meaning these components are already 'migrated' to cloud services provided by others, simplifying their management. However, the core 'Cato SASE Cloud Platform' is built on 'Bare-metal compute servers (custom PoP infrastructure, no hyperscaler dependency)'. While this provides independence and avoids hyperscaler lock-in for its primary offering, it also means that a fundamental migration of this core platform to a public cloud IaaS (e.g., AWS, Azure, GCP) would constitute a significant re-platforming effort rather than a straightforward lift-and-shift. This custom bare-metal foundation is the primary factor limiting a higher migration readiness score for a complete infrastructure overhaul. Similar to resilience, the 'Total Vendors: 0' in the 'Vendor Relationships' section is inconsistent with other data. Assuming the numerous third-party services listed in the 'Internal Tech Stack' represent vendor dependencies, Cato Networks utilizes a diverse set of vendors for its internal operations. While this reduces overall vendor lock-in for internal tools, migrating between these SaaS platforms can still present challenges. The company's strong regulatory compliance ('GDPR, HIPAA, CCPA, SOC 2 Type 2, ISO 27001, NIS2 Applicable') and 'global network of 80+ PoPs' supporting data residency, while strengths for operations, would add complexity and stringent requirements to any large-scale migration project. The absence of financial stability data ('Revenue Concentration by Product', 'Revenue Concentration by Geography', 'Growth History') also limits the assessment of its capacity to fund a major migration initiative.
Compliance
14 in-scope frameworks identified; showing 3.
ISO 27001 (source) — Compliant
Cato Networks explicitly holds ISO/IEC 27001:2013 certification, confirmed on its official Security, Compliance and Privacy page. This is independently audited by an accredited certification body. ISO 27001 is the globally recognized standard for Information Security Management Systems (ISMS) and is directly applicable to Cato as a cybersecurity and cloud services company. Risk is Low because the certification is current, independently validated, and publicly disclosed. The company also holds ISO 27017 (cloud security), ISO 27018 (PII in cloud), and ISO 27701 (privacy management) — demonstrating a comprehensive ISO 27000-series compliance posture. The footer of the main website prominently displays 'ISO 27001 Certified.'
Evidence: https://www.catonetworks.com/security-compliance-and-privacy/, http://security.catonetworks.com/
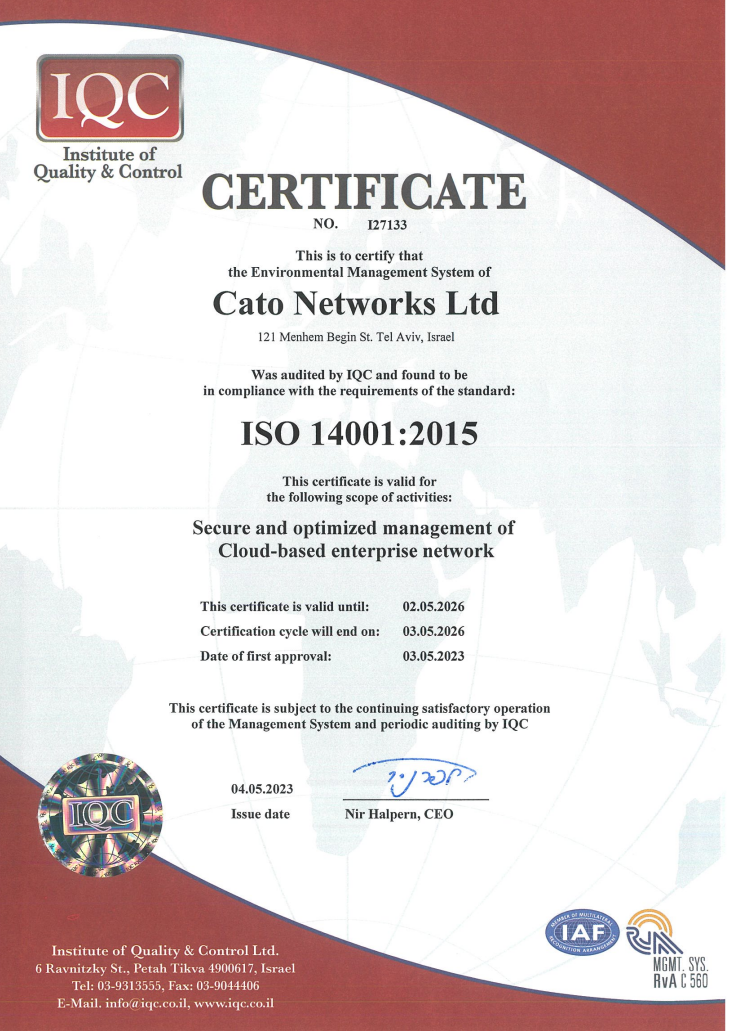
ISO 14001 — Compliant
Cato Networks holds ISO/IEC 14001:2015 certification (Environmental Management System), confirmed on its official Security, Compliance and Privacy page. While not a cybersecurity regulation, this demonstrates Cato's commitment to environmental compliance relevant to its global data center and PoP operations. Risk is Low because the certification is independently audited and publicly disclosed.
Evidence: https://www.catonetworks.com/security-compliance-and-privacy/, https://go.catonetworks.com/rs/245-RJK-441/images/ISOIEC_14001201_EN.png
UK Cyber Essentials — Compliant
Cato Networks holds UK Cyber Essentials certification, confirmed on its official Security, Compliance and Privacy page with a certificate linked. This is relevant for Cato's UK operations and UK customer base. Risk is Low because the certification is independently validated and publicly disclosed.
Evidence: https://www.catonetworks.com/security-compliance-and-privacy/, https://go.catonetworks.com/rs/245-RJK-441/images/48ba4947-e4ce-4116-8f32-9fdaec59ee55_certificate.pdf
Financials
Three-year financials
- 2024: revenue USD $250M+ ARR
- 2023: revenue USD $200M ARR
- 2022: revenue USD $130M ARR
Financial Resilience Score: 8/10
Cato Networks demonstrates strong financial resilience for a private, late-stage cybersecurity company. It has raised over USD $1.1B cumulatively, including a fresh USD $359M late-stage round in 2024 reported by WSJ, providing ample runway. Its subscription-based SASE platform delivers high revenue visibility, strong gross retention, and recurring revenue characteristics that are inherently resilient. ARR has grown from ~$100M in 2021 to over $200M by end of 2023 (>59% YoY), and reportedly toward $250M+ by early 2025, placing Cato among the fastest-growing cybersecurity firms in its cohort. The company's institutional investor base (Lightspeed, Greylock, USVP, Coatue, Adams Street, Singtel Innov8, ION Crossover) supports future IPO readiness, and founder Shlomo Kramer's track record (Check Point, Imperva) adds credibility. Cato is recognized as a Leader in Gartner's 2025 SASE Platforms Magic Quadrant, reinforcing category leadership in a fast-growing segment. However, profitability remains undisclosed and the company almost certainly still operates at a loss given its growth-stage investment profile. Private-company opacity, intense competition from Zscaler, Palo Alto Networks, Cisco, Fortinet, Cloudflare, Netskope, and Versa, plus Israel-centric R&D concentration, temper the score. Overall resilience is solid but not verifiable at audited-financials level.
Key strengths: Over USD $1.1B cumulative equity funding raised, Fresh $359M late-stage round in 2024 providing significant runway, Top-tier institutional investor base (Lightspeed, Greylock, Coatue, USVP), Subscription/recurring revenue model with high visibility, ARR growth >59% YoY reaching $200M+ in 2023, Gartner Magic Quadrant Leader for SASE Platforms (2025), Founder pedigree - Shlomo Kramer (Check Point, Imperva), 4,000+ enterprise customers with no disclosed concentration, Category leadership in fast-growing SASE segment
Risk factors: Profitability/EBIT not disclosed - likely still cash-burning, Private-company opacity limits financial verification, Intense competition from larger public rivals (Zscaler, Palo Alto Networks, Cisco, Fortinet, Cloudflare, Netskope), Israel country/geopolitical exposure with R&D concentration, Exit dependency at ~$4-5B valuation requires IPO or strategic sale, No audited financial statements publicly available, Unknown cash burn rate and customer concentration
Revenue by geography
- Americas (mostly U.S.): 50%
- EMEA: 35%
- APAC and LATAM: 15%
Revenue by product/service
- SASE Cloud Subscription (SD-WAN, FWaaS, SWG, ZTNA, CASB, DLP, IPS, XDR): 90%
- Hardware (Sockets) and Professional Services: 10%
Workforce by country
- Total Global: 1100
- Israel: 0
- United States: 0
- United Kingdom: 0
Signed-in users can see whether their own company is exposed to this vendor's disruption, plus the full sub-vendor list and country breakdowns, every in-scope compliance framework plus gaps and next steps, and alerts when any of it changes.